06 October 2026
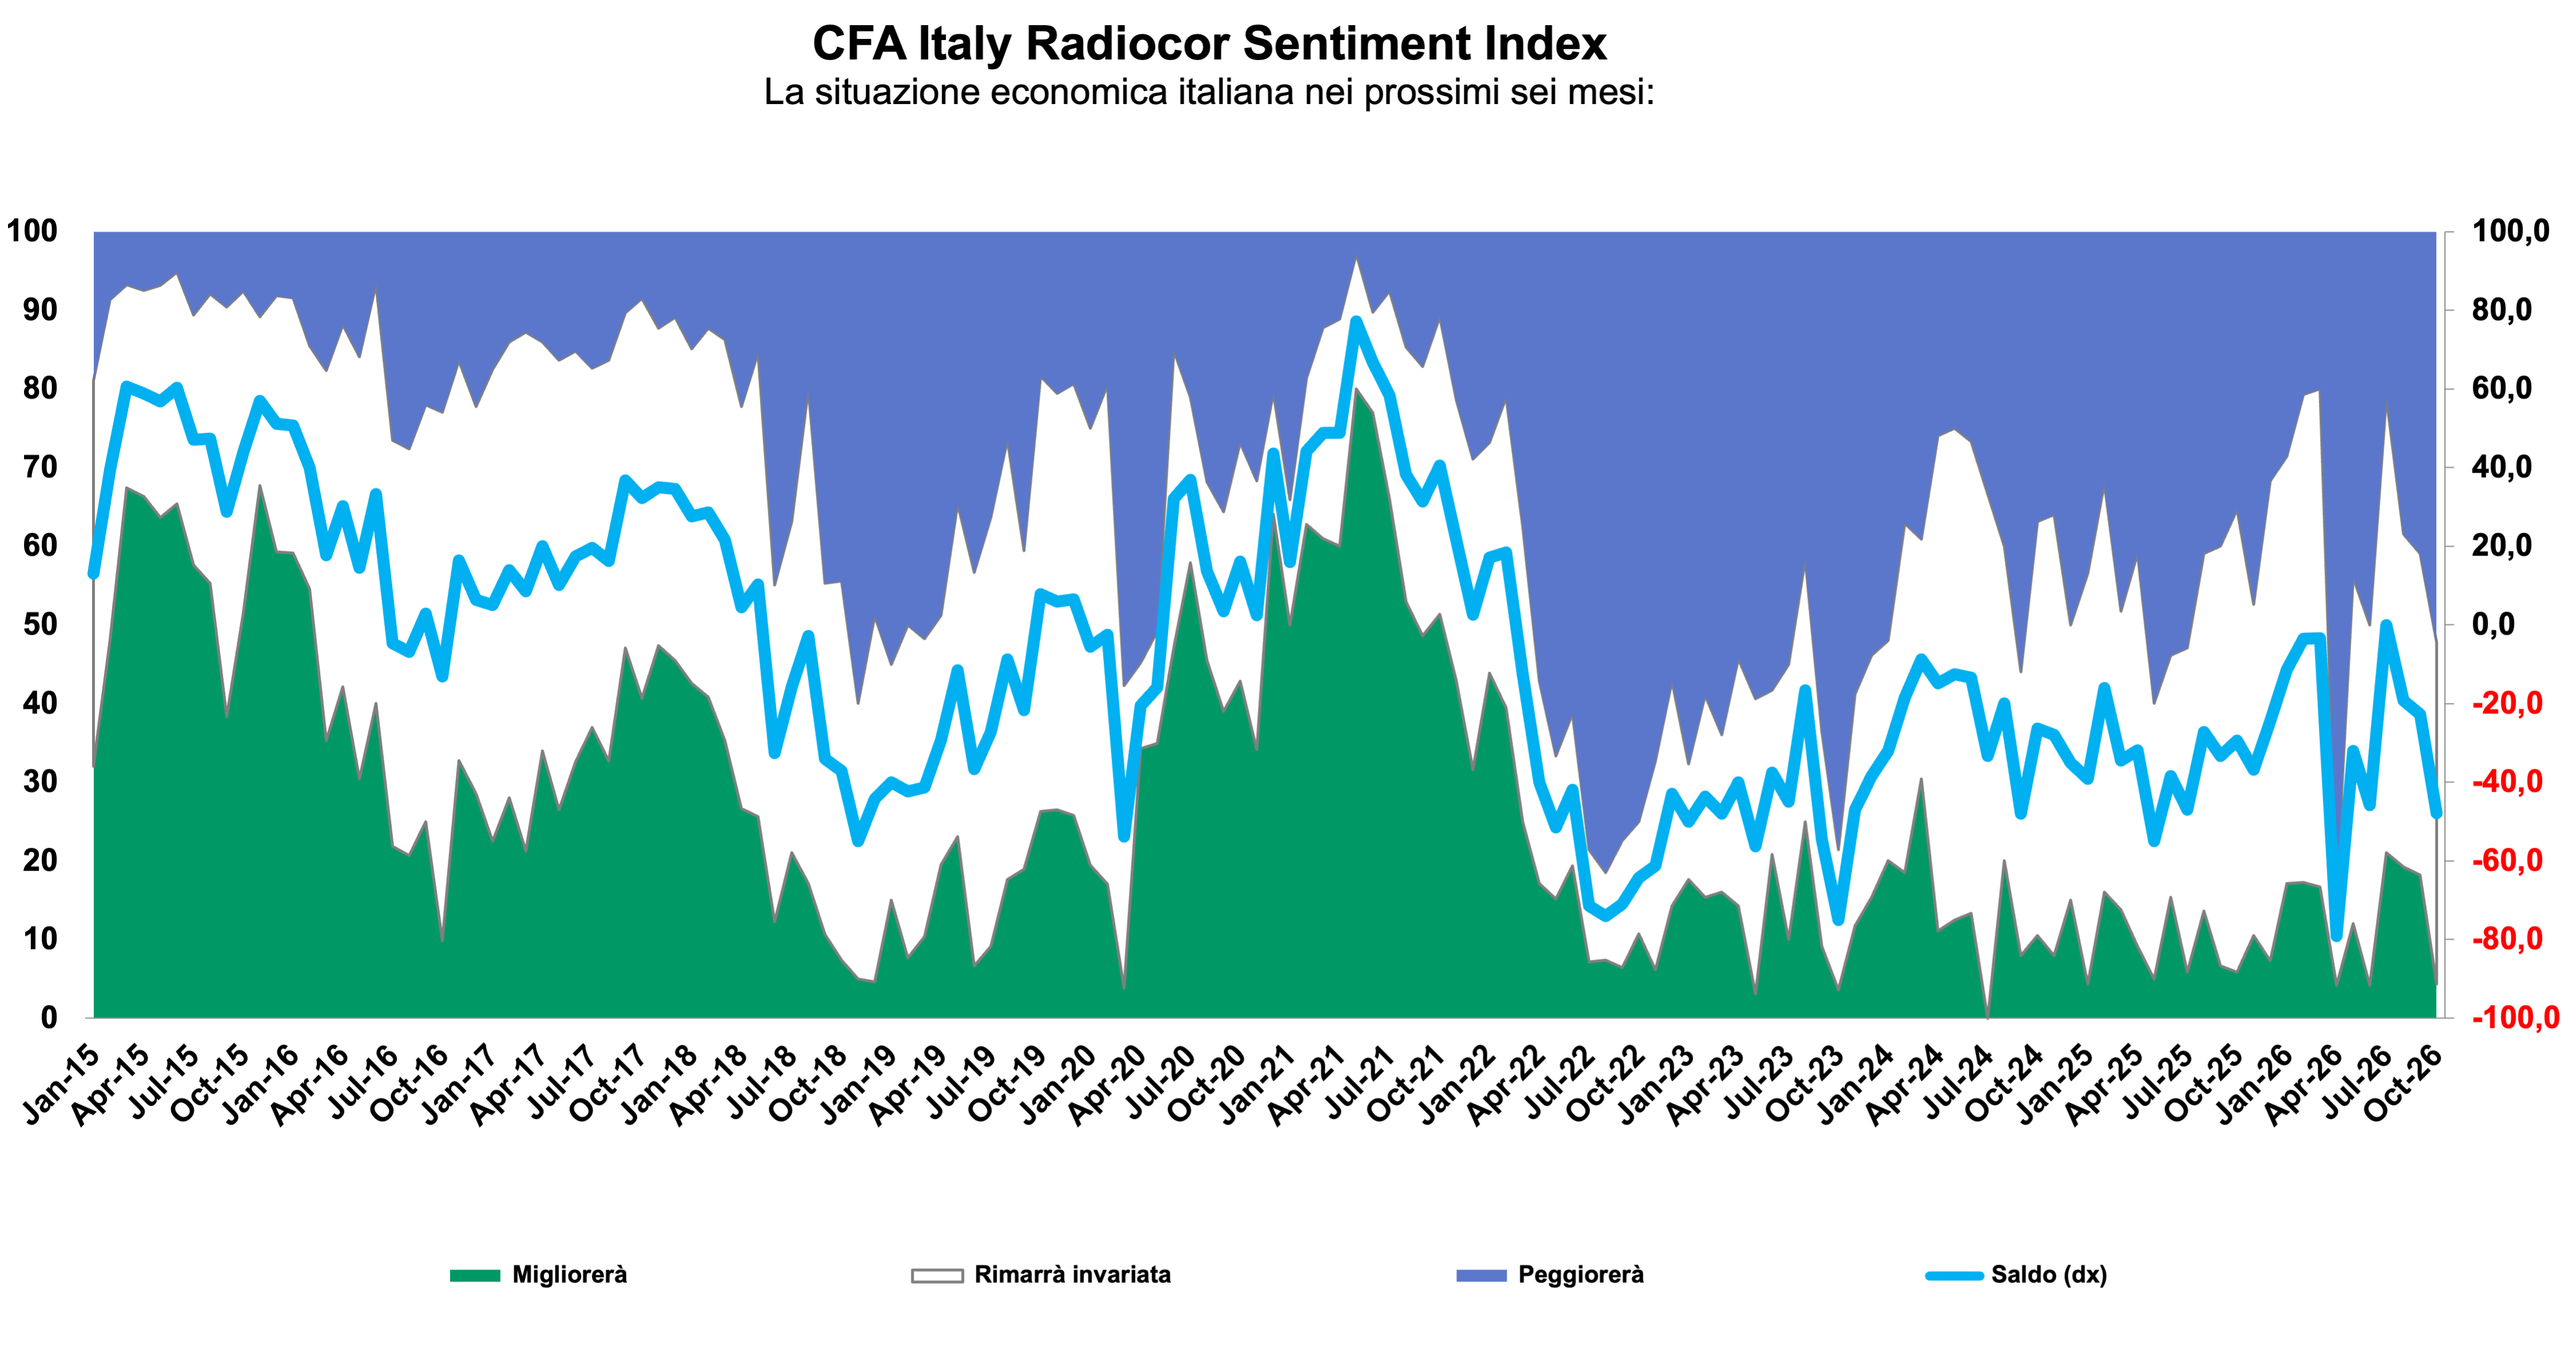
The outlook among Italian financial professionals has deteriorated sharply. The CFA Society Italy-Radiocor Sentiment Index fell to -47.8 points in October, more than 25 points below the previous reading, as concerns over weaker economic growth combined with renewed inflationary pressures.
The latest CFA Society Italy-Radiocor Financial Business Survey, conducted in collaboration with Il Sole 24 Ore Radiocor between 19 and 30 September 2026 among CFA Society Italy members, reveals a growing divergence between perceptions of current economic conditions, which remain broadly stable, and expectations for the months ahead.
Current conditions hold, but expectations weaken
The assessment of Italy’s current economic situation has changed relatively little. 70.8% of respondents describe conditions as stable, compared with 20.8% who view them negatively and 8.3% positively. The balance between positive and negative assessments improves slightly to -12.5 points, suggesting that the present environment remains weak but has yet to show signs of a pronounced deterioration.
The six-month outlook tells a very different story.
The Sentiment Index drops to -47.8 points, its lowest level in recent months. More than half of respondents (52.2%) expect the Italian economy to deteriorate over the next six months, while only 4.3% anticipate an improvement.
Caution extends well beyond Italy. The expectations balance for the Eurozone falls to -41.7 points, while the corresponding indicator for the United States stands at -34.8 points, pointing to concerns about the broader international economic outlook.
Inflation returns to the forefront
One of the most significant shifts in the October survey concerns inflation.
Following the recent acceleration in European energy prices, respondents have substantially revised their expectations upwards. In both Italy and the Eurozone, the balance between those anticipating higher and lower inflation rises to 39.1 points, more than double the previous month’s reading.
The increase comes as higher natural gas prices bring European energy risks back into focus, raising concerns that increased energy costs could feed through to consumer prices over the coming months.
Inflation expectations are even stronger in the United States, where the balance reaches 52.2 points, confirming that price pressures remain a major concern for financial professionals.
Rate expectations rise sharply
The renewed inflation concerns translate into a decisive shift in interest rate expectations.
For short-term rates, the balances climb to 79.2 points in Italy, 83.3 points in the Eurozone and 87.5 points in the United States. The readings indicate a strong expectation that monetary conditions will remain restrictive.
Respondents also anticipate upward pressure on long-term yields, although less pronounced than at the short end of the curve. The balances stand at 29.2 points for Italy, 25 points for the Eurozone and 37.5 points for the United States.
Together, the results suggest that investors are increasingly incorporating a combination of persistent price pressures and relatively tight financial conditions into their outlook.
Equity sentiment turns negative across all major markets
The weaker macroeconomic outlook is also reflected in equity-market expectations. For the first time in this month’s picture, all four major indices covered by the survey record negative balances.
The FTSE MIB falls to -13.6 points, while the FTSE STAR reaches -28.6 points. The balance for the Euro Stoxx 50 stands at -18.2 points, with sentiment towards the S&P 500 even weaker at -31.8 points.
At sector level, however, the picture remains highly differentiated.
The oil sector records the strongest expectations, with a balance of 50 points, benefiting from the current energy environment. Banks follow at 36.8 points, supported by expectations of higher interest rates, while utilities stand at 31.6 points.
Cyclical sectors remain firmly out of favour. Automotive records a balance of -73.7 points, followed by construction at -68.4 points and industrial machinery at -50 points.
Yen strengthens in respondents’ expectations
In foreign exchange markets, respondents continue to expect the US dollar to weaken against the euro, although the conviction is less pronounced than in September. The balance stands at -17.4 points.
Expectations for the Japanese yen, by contrast, strengthen considerably, with the balance rising to 36.4 points.
Finally, despite the recent increase in energy prices and the strong outlook for oil-sector equities, respondents have become more cautious about the medium-term direction of oil prices themselves. 36.4% expect prices to decline over the next six months, compared with 22.7% anticipating an increase. The balance consequently falls back into negative territory at -13.6 points, reversing the positive expectations recorded in the previous survey.
The October results mark a clear change in tone. While financial professionals do not yet see a pronounced deterioration in Italy’s current economic conditions, their expectations for the months ahead have weakened substantially. At the same time, the return of inflation concerns – particularly against the backdrop of higher energy prices – is reshaping expectations for interest rates and contributing to greater caution across equity markets.
The press release can be found here.